01 · 4 October 2021 / 19 January 2022The Service asked for a hold—then asked again
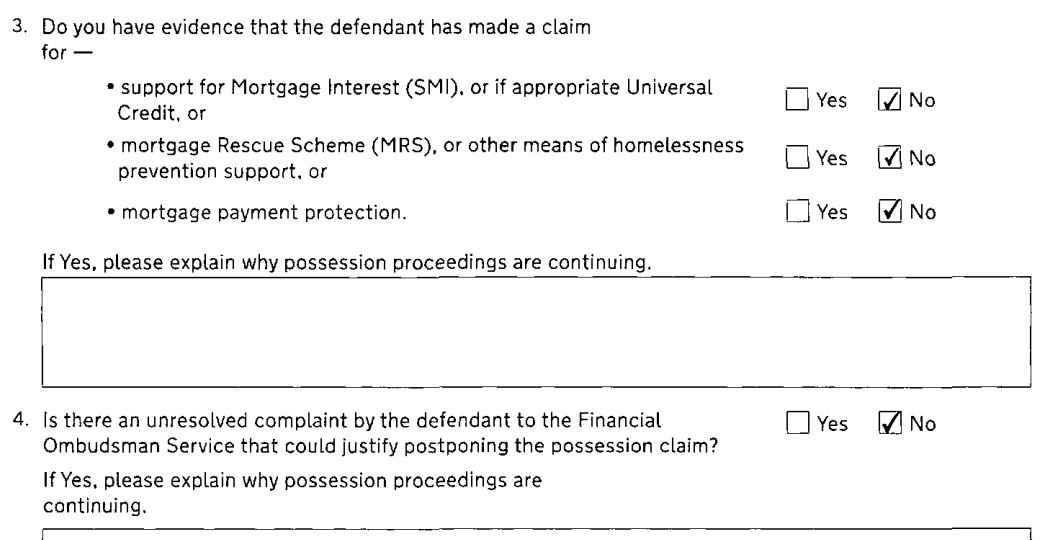
In its 19 January reminder, the Financial Ombudsman Service said it had asked on 4 October 2021 for the proceedings to be put on hold while it considered my case. That request was not a court stay, but it called for an answer from the firm.
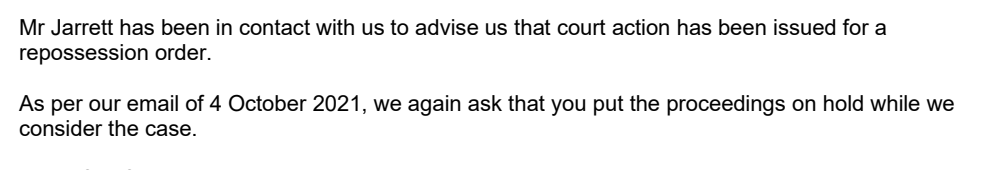
Co-op DSAR 3, physical p.145; cropped image of the reminder reproduced in the Bank’s file.
02 · 19 January 2022The proposed response: charge me for the pause
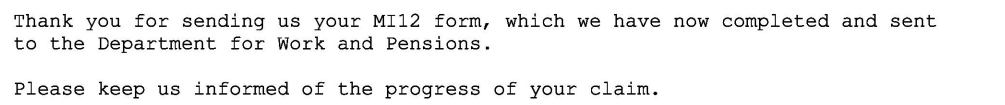
A Western Mortgage Services manager (the servicer) proposed telling FOS that proceedings had begun before its October email. He also proposed that the costs of adjourning the hearing be added to my mortgage. His internal email put the arrears at £17,598.
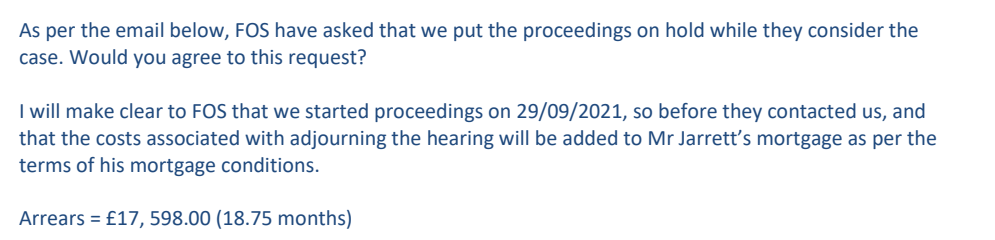
Co-op DSAR 3, physical pp.143–144; the operative passage is on p.144. This was an internal proposal, followed by the actual response below.
03 · 20 January 2022The reply invoked my vulnerability—and charged for delay
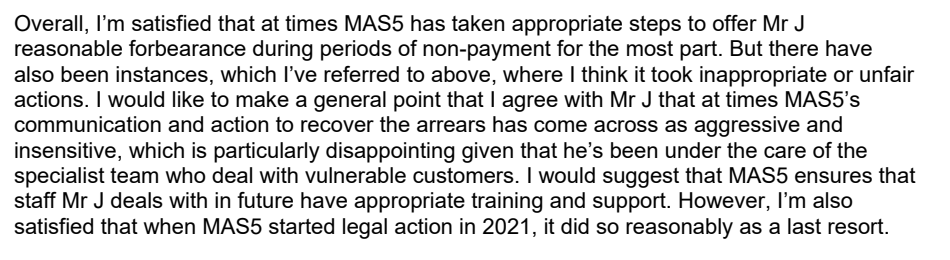
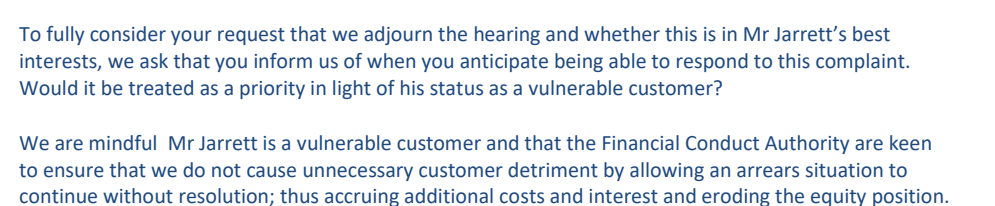
The response sent to FOS asked whether adjourning was in my interests. It invoked my vulnerability, the FCA’s concern about accumulating costs and interest, and an asserted £17,598 arrears. It then said the costs of adjournment would be added to my mortgage and duplicated if the hearing had to be restored.
Co-op DSAR 3, physical pp.14–15. These are cropped passages from the response, not the complete two-page email. The financial premise needs to be tested against the Bank’s later £0 reconstruction for 19 January.
04 · 26 January 2022The original request had not been noticed
The manager then acknowledged internally that “no-one (including me) noticed” the request in FOS’s 4 October email to put possession proceedings on hold. Later that day, a Co-operative Bank manager wrote that she was prepared to adjourn and asked Capita to obtain confirmation.

Co-op DSAR 3, physical pp.137–138. Read the full 26 January Bank email shown on the April 2019 page → The court’s actual order appears below.
05 · 14 February 2022The court struck the claim out
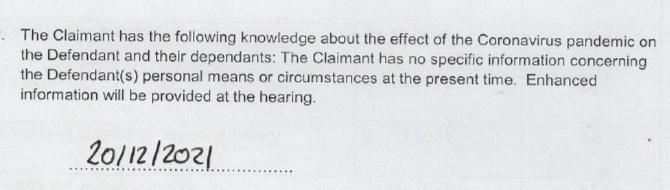
Before the hearing I wrote to the judge, challenged the claimant’s answers about my SMI application and circumstances, and expressly asked to be heard or for the claim to be struck out. I believe my submission mattered. The court order does not give the judge’s reason.

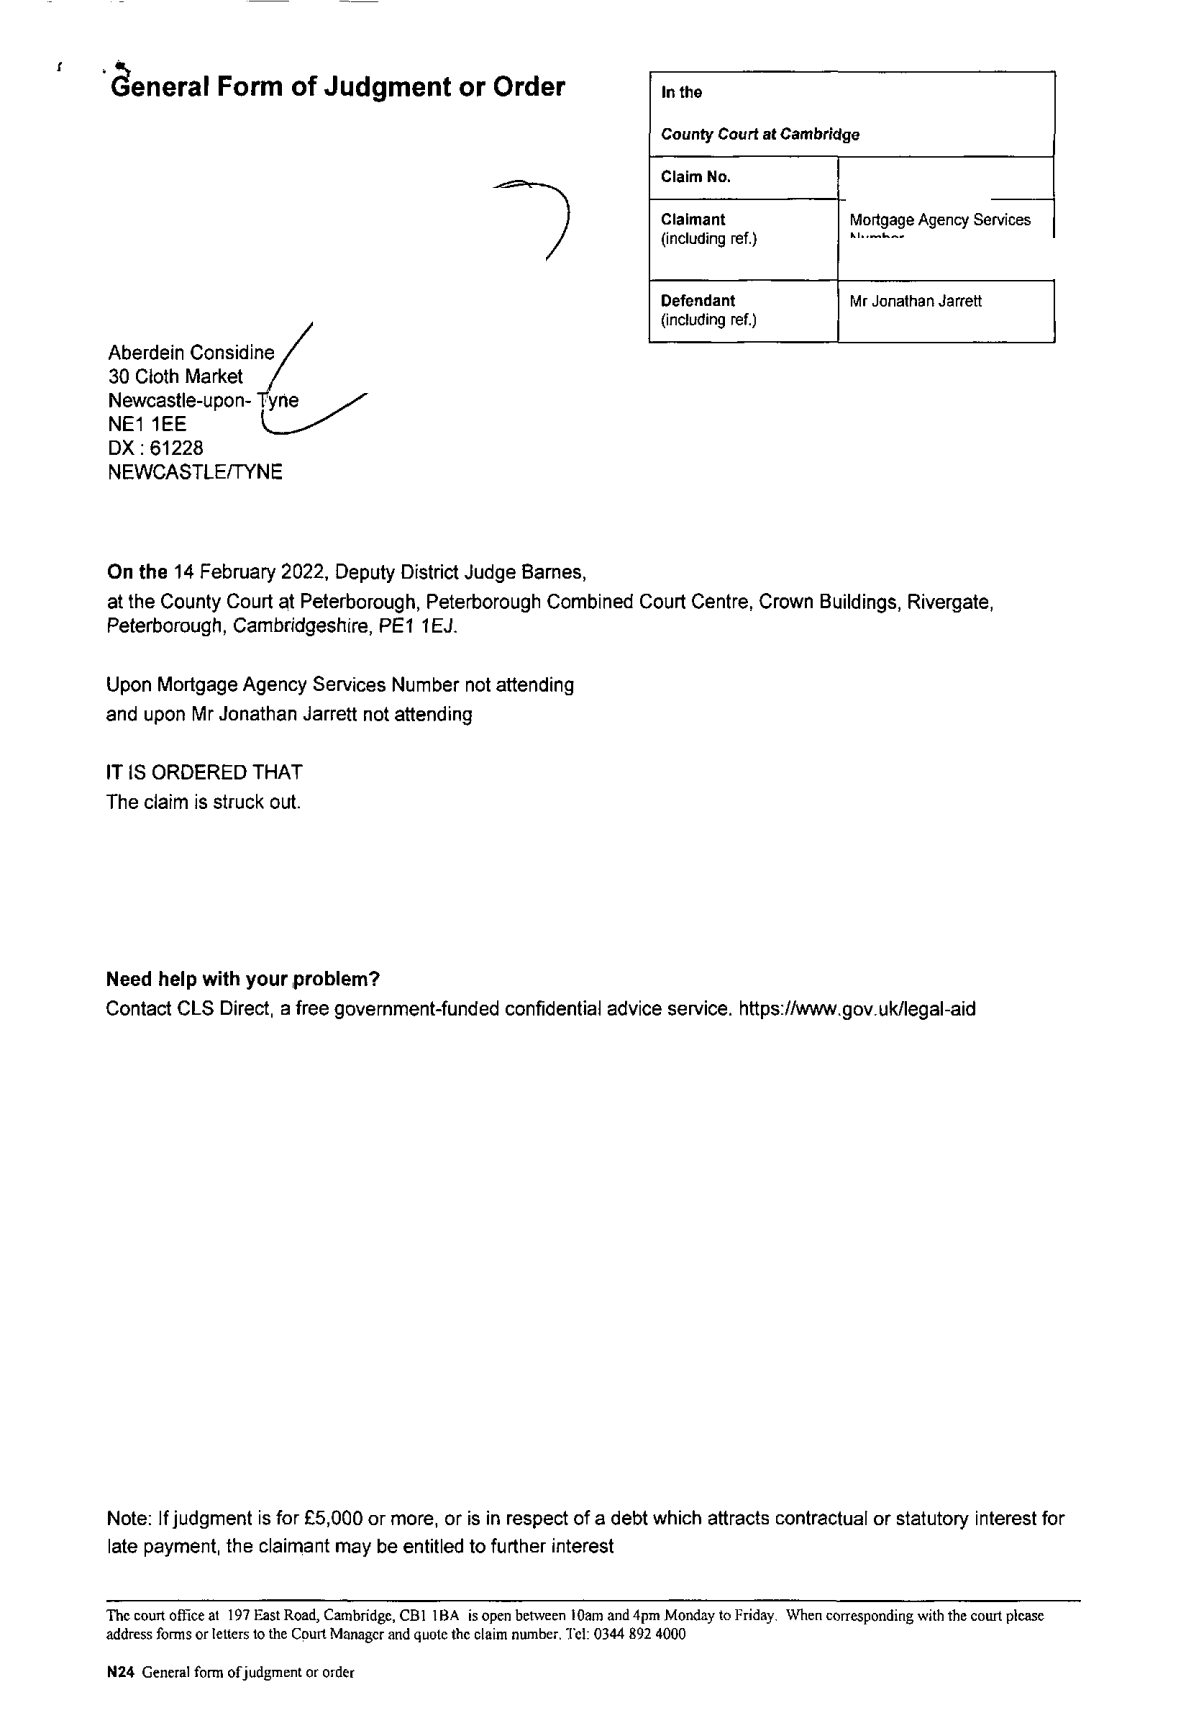
Deputy District Judge Barnes’s order says: “The claim is struck out.” It records that neither the claimant nor I attended. This was the court’s disposition of the claim; the order does not say it was adjourned or decide the merits of my mortgage complaint.

My court submission: E-LIT-33, pp.2, 15 and 17; the selected 43-46.pdf, p.4, contains the closing passage shown above. Court order: County Court at Cambridge, General Form of Judgment or Order, 14 February 2022, p.1. Select the order extract to view the full page with account and case references masked. The separately addressed copy contains my home address and is not in the website package.
06 · 23 March 2022£839.80 in legal costs added
After the strike-out, MAS5 wrote that it had paid £839.80 to its solicitors and applied that amount to my mortgage account. It warned that this might not be the final total if further action followed. I ask how these costs were justified and whether they were later refunded with any interest charged on them.
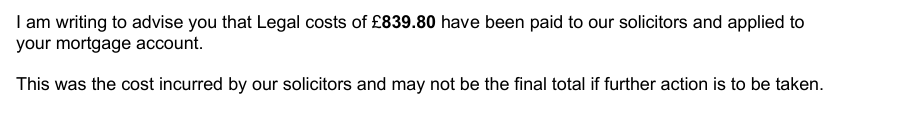
MAS5 letter of 23 March 2022, Jon’s selected legal_fees_letter.png; cropped body only. The address, account number and reference are excluded.
07 · 16 June 2022Their own later record confirms the difference
A servicing note reproducing the solicitors’ email says they were instructed on 26 January to adjourn, “The claim was subsequently struck out”, and they had asked the court to reconsider and adjourn it instead. The note says the court advised that an application would be needed. That is not a record of an adjournment having been ordered.
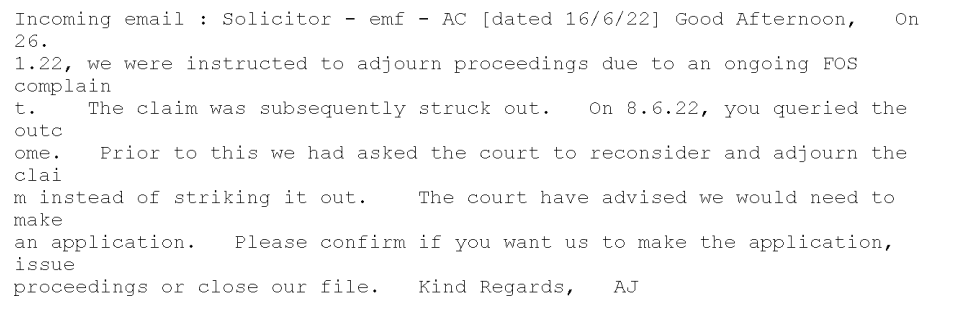
E-INT-04, p.2, servicing note; p.1 contains the forwarded solicitor email. The visible source text is imperfectly transcribed in the file, so the court order above controls the actual outcome.